The African regionmhas become a more attractive locale of late for modern banks hoping to depart from legacy markets. In places such as the Gambia—where talks about opening up an offshore bank license are creating a wave of new optimism for the future—the space for banks to offer digitally progressive services is massive. Yet while this is a commendable commitment, it comes with its complications. From stymied regulation to spotty infrastructure, and the necessity of respecting local culture while grappling with uneven financial literacy, banking in Africa takes more than money — it takes adaptability. The reward? Real opportunities, not only to reach new African market but to help frame the economy and be a force for good for hundreds of thousands.
Explore mobile payment opportunities in Africa
- A Leapfrog Moment
Forget everything you know of the old world of banking infrastructure. Across much of the African continent, people didn’t start with financial institutions branches, then add ATM cards and then eventually use electronic transfers — they started with cellphones. From M-Pesa in Kenya to MTN Mobile Money in West Africa, mobile-first finance has thrown out the rule book. Traditional banks should not see this as competition, but a guide map. The difficult part — getting to the unbanked — has been accomplished by the mobile payment titans. Finally, there will be an opportunity for banks to participate as opposed to compete, through layers of services, such as savings, insurance, lending, contained within their own digital ecosystems. Why replicate the wheel when collaborations can achieve faster, more meaningful traction?
- Creating New Financial Pathways
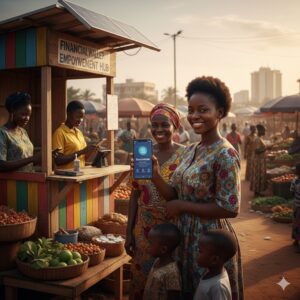
Picture a woman in rural Ghana who is storing away a few cedis at a time in a mobile wallet. But a year ago she borrowed a modest sum from an app, used it to buy grain, and made a modest but steady profit. These are the kinds of boots-on-the-ground stories that banks should pay attention to. And when you pair mobile payments with real-world touchpoints like local agents, kiosks, community centers, you create a presence that is not just about delivering services, but also conveying trustworthiness.
Address regulatory and compliance challenges
- Diverse Regulatory Hurdles
Africa is not a market; it is 50-plus other markets, each with its quirks. The Nigerian Central Bank has tight FX limits, the Financial Intelligence Centre in South Africa has a hawkish reporting stance, in Ethiopia, it remains evolving; in Congo, it is frequently murky. Compliance cannot be one-size-fits-all; it must conform to both global rules and local laws. Beyond law, there’s a more subtle something: the adaptation of your business and governance practices to local culture.
- The Cost of Compliance
Yes, compliance is expensive. But it’s also your credibility. From anti-money laundering systems to customer files, each layer of compliance telegraphs your seriousness. Even those digital banks are mandated to obtain authorization to provide mobile services in Nigeria — evidence now that regulation matters in this fast-digitizing economy. Look at compliance not as a barrier (although in some cases it is), but as a mark of trust in markets in which that’s a premium currency.
Adapt services to local economic and cultural needs
- Understanding the Cultural Mosaic
Diversity in Africa is just too much — more than 2,000 languages, uncounted customs, and varied monetary practices. In Ghana, susu groups are about more than just saving — they’re rituals of community. Business in Nigeria is personal relationship-based. Launching a Western-style banking product without a wink to culture? That is a fast route to irrelevancy. Those banks that make it will be the ones that listen before they build. Apps that synchronize with harvest cycles, interfaces in local dialects, or products based on social lending — all are examples of cultural intelligence. And that translates to adoption.
- The Importance of Financial Literacy
It doesn’t matter that your app looks great if your customers can’t — or won’t — use it. Very few communities are in contact with the formal financial sector, let alone smartphones. That’s where literacy programs come in. Imagine banks providing mobile tutorials, underwriting radio shows on the topic of budgeting, or collaborating with schools to infuse basic money management into the curriculum.
Invest in infrastructure and financial literacy programs
- Tech Reliability vs. Reality
Erratic internet, rolling blackouts, and scarce access to reliable power remain real challenges. But smart tech can step in to fill the void. Apps based on a principle of offline-first use, USSD systems which don’t need smartphones, and solar-powered service kiosks are some examples of creative workarounds that are being used already. And beyond tech? People. Branchless banking models — methods in which mobile agents take services into communities — scale in areas where digital infrastructure is insufficient on its own.
- Local Innovation Labs
Africa does not need new innovation to come from outside — it is happening at home. Hubs, such as Kenya’s iHub and Nigeria’s Co-Creation Hub, are developing payment products, experimenting with the blockchain, and building microloan apps tailored to local realities. Banks buying into these ecosystems are investing in R&D dollars, not just as a final source of their best ideas but as co-creators. This kind of collaboration produces tools that are born of actual pain points, created by the people who feel them most.
Roadmap Forward
In order for institutions to be able to survive and thrive in the African financial ecosystem, they need to focus on six overlapping areas of action:
- Solution Services
Develop mobile-first products such as credit, savings, insurance, and remittances for the daily realities. - Infrastructure
Invest in: offline-first apps, solar-powered kiosks, and an agent-led distribution model to reach the last mile. - Compliance
Build local relationships and strengthen KYC/AML in response to varying regulatory requirements. - Literacy & Culture
Provide financial literacy in indigenous languages and build around the actual ways people interact socially. - Inclusive Economy
Facilitate micro and small business financing and ease diaspora remittances for families dispersed.
Conclusion
Africa is not a blank slate on which global banks can write new stories — it’s a thriving ecosystem with its rhythm, challenges, and ingenuity. With the mobile payments revolution transforming access and quickly revealing what infrastructure is actually capable of providing, and literacy levels improving, there’s an opportunity for deliberate engagement. The institutions that are listening, adapting, and respecting the delicate mosaic of culture, compliance, and community will thrive, and not just survive — they will be the leaders of the next generation. They’re going to make profits, not just profits — they’re going to make a difference.